
The Calm Before The Volatility
I definitely need to preface this article with the Not Investment Advice disclaimer. A couple months ago I refused to make a weekend pick because nothing looked good. This week it’s because almost everything does. Do your own research, I’m not losing your money for you.
Volatility rank and volatility level have come completely apart, and in directions we usually don’t expect to see. The** loudest, most speculative corners**of this market are trading at 52-week implied vol floors, while the blue chips in energy are the only things where it’s going up.

The TLDR of this whole article - if you’ve been considering options on your favorite stocks, and have got the stomach to hold through some news which may whiplash the market this week and next - options are currently priced perfectly for buying, not wheeling, with IV ranks near zero across the speculative end of the board.
$VIX and the regime
VIX 15.84, VVIX ~91, both down roughly 11% togetheron Friday’s in-line CPI (3.4% vs 3.4% consensus). Per @Math & Cynce’s rule that’s confirming, not diverging, so this is an honest post-catalyst vol crush and not a warning dressed as calm. VIX sits in the bottom third of its 52-week band (13.38 to 35.30). Underneath that calm, credit is quietly going the other way: HYG and JNK are both under their 50dma and high-yield spreads widened 7bps in ten days. Hold that thought, it comes back at the end.
Gamma, reconciled:** index level is long gamma** (SPX flip 7648, spot 7657, max-gamma pin 7675; $SPY and $QQQ both just above flip), small caps are short gamma ($IWM flip 290.72 with spot below it and a 3.35 put skew, $DIA short too). So a shock gets absorbed at the index and amplified in small caps. $NVDA specifically sits 0.4% above its own flip at 217.36, pin at 220.
WTF did I just say, and what does it mean?
Let’s take a look at the IV rank of some of the biggest stocks in the semiconductor market. For the uninformed, IV rank measures where today’s implied volatility sits inside that stock’s own 52-week IV range. A rank of 0 means options on that name are the cheapest they’ve been all year. A rank of 100 means the most expensive. Note what it does not tell you: the actual level. A stock can print a rank of 2 and still be charging 68% IV, which is exactly what happens further down this page.

Eleven of fourteen are cheap or at the annual floor. The pattern is hard to miss: the bigger and more owned the AI name, the deader its options. NVDA was the most newsy ticker in the entire group this week (Burry dumping puts, a reported ~$10B Anthropic IPO stake) and its implied vol is at a 52-week low. **That’s not an all-clear.**That’s “everyone already owns it and there’s nothing left to reprice.”
What premium exists is in the second tier (ARM, INTC, LRCX, QCOM), and none of those three highest-rank names has an actual catalyst behind it. It’s residual chop, not event premium.
$MU 9/30 AMC is the only confirmed earnings in the window($438M pre-earnings premium, sentiment split 51/49). The others did not appear in the 28-day feed, which means unconfirmed, not absent.
Space: the cleanest rank-vs-level split on the board
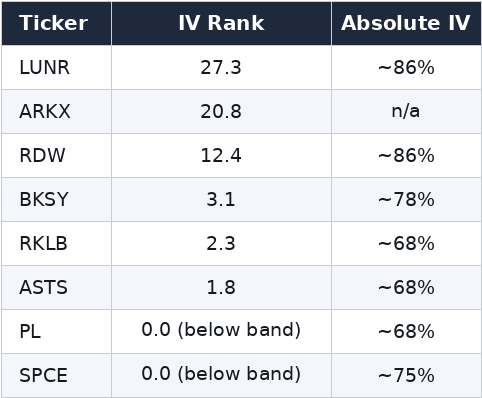
$RKLB and $ASTS read as the cheapest vol they’ve offered in a year while still charging 68%. Three times what $LMT (24%) and $RTX (23%) charge. $PL and $SPCE are clamped below their 52-week floor and still running 68 to 75 percent, and SPCE’s absolute IV actually rose 16.7% over five sessions while its rank printed zero. The whole distribution shifted up underneath a rank that says nothing is happening.
Short interest: ASTS is the one with fuel, 7.25 days to cover and shorts up 11.6% on the settlement. RKLB 3.06 days, LUNR 4.43, RDW 3.39.
Neither RKLB nor ASTS has a catalyst in the news feed right now. RKLB had a routine 16th Electron launch, ASTS has literally zero headlines.
What else looks like that
The floor club, all sitting at or below their 52-week IV band while carrying huge nominal premium:
- Nuclear and power: $OKLO 0.0 rank / ~69% IV, $SMR 0.25 / ~75%, $CEG 7.7 / ~40%
- Quantum and spec AI: $IONQ 0.0 / ~73%, $QBTS 1.4 / ~69%, $BBAI 0.7 / ~66%, $SOUN 1.3 / ~60%
- Crypto-adjacent: $IBIT 7.9, $RIOT 13.9 / ~80%, $MSTR 25.3 / ~68%
- Megacap tech: $MSFT literally 0.0 rank, $GOOGL 13.8, $NFLX 18.1, $AMZN 21.4, $TSLA 21.4
- Retail favorites: SOFI 6.5, PLTR 15.1
Same signature as RKLB and NVDA. Structurally re-based vol, cheap by history, still loud in dollar terms.
One live one from the screener: SMR moved -15.7% in a single session on 3.2x volume with an IV rank of 0.2. Realized vol spiking while implied stays pinned at the floor is an IV-repricing lag, and it’s the most interesting single data point in the whole sweep of data. The options market had a quiet week priced in for a stock that fell 15.7% in a single session. Somebody’s model needs a hug.
What doesn’t look like that
The rich list is almost comically boring:

Energy, rates, staples, pharma. Quiet names whose premium is expensive relative to their own quiet history. XLE is also the only sector besides XLK flagged as all-cylinders bullish on flow plus technicals plus price, so rich vol there reflects real two-sided positioning around a live trend rather than stale premium. That’s the one place on the board where rich vol and a real move agree.
Metals are the no-edge middle: GLD 28.8, SLV 32.4, GDX 39.1, NEM 29.2. Nothing to do. FCX’s +12% five-day IV pop is the only thing worth a watch.
Data caveats
-
Everything is Friday 9/11’s close. It’s Saturday afternoon.
-
A lot of names clamped below their 52-week band at once. Given VIX is genuinely in the bottom third of its own year that’s probably real, and there’s honest dispersion in the data (0 to 61) rather than one verdict printing everywhere, so it doesn’t smell like the falsy-default bug. But it’s enough simultaneous floor-clamping to be worth knowing about.
-
The risk-on read (call/put 2.03, +$455M into calls) and the bearish index put/call (SPY 1.86, QQQ 2.57, IWM 2.16) are not a contradiction. Single names are getting call-bought while the index gets hedged into FOMC and opex. The $73.4M SPY 766 put print was 9/11 expiry, already dead, ignore it.
Please read that last one again if you want to trade this week. Here, let me repeat the important part:
Single names are getting call-bought while the index gets hedged into FOMC and opex
What I’d actually do with this
Don’t sell premium in the floor club on the rank alone. You’d be selling the cheapest vol those names have offered in twelve months on tickers that can drop 15% in a session, and SMR just proved it. If you want the shares anyway that’s a defensible wheel. If you’re selling for the credit, you’re getting paid the least you’ve been paid all year for that exact risk.
The rich-vol premium sale is $XOM, not the space and semi names. IV rank 61, a real uptrend behind it, and energy is one of only two sectors with flow and technicals aligned.
**If you want long optionality, this is the cheapest it’s been.**RKLB, ASTS, OKLO, IONQ, and megacap tech are all at or below their annual IV floors going into FOMC Wednesday and quad witching Friday, with contango saying the market itself thinks vol is coming back. The asymmetry is sitting right there.
One warning on how you express that. The obvious move Monday morning is to go buy UVXY or VXX and wait for the fireworks. Don’t. Three-month VIX sits at 18.60 against spot 15.84, and that gap is not free money, it’s the roll cost you pay every day you hold those things. The curve is steep precisely because everybody already agrees vol is coming back. You are not early to that trade, you are just paying rent on it. Buy the optionality on the single names instead, where a 52-week floor rank means you actually get the cheap vol rather than renting somebody else’s.
**Watch credit, not VIX. $**HYG and $JNK below the 50dma with spreads widening while VIX prints 15 is the actual tell in this data.
It’s going to be a fun week. New millionaires will be minted - these are the weeks fortunes can be made (and lost).