
Amazon and I Own Qualcomm From the Same Price (Seven Cents Apart)
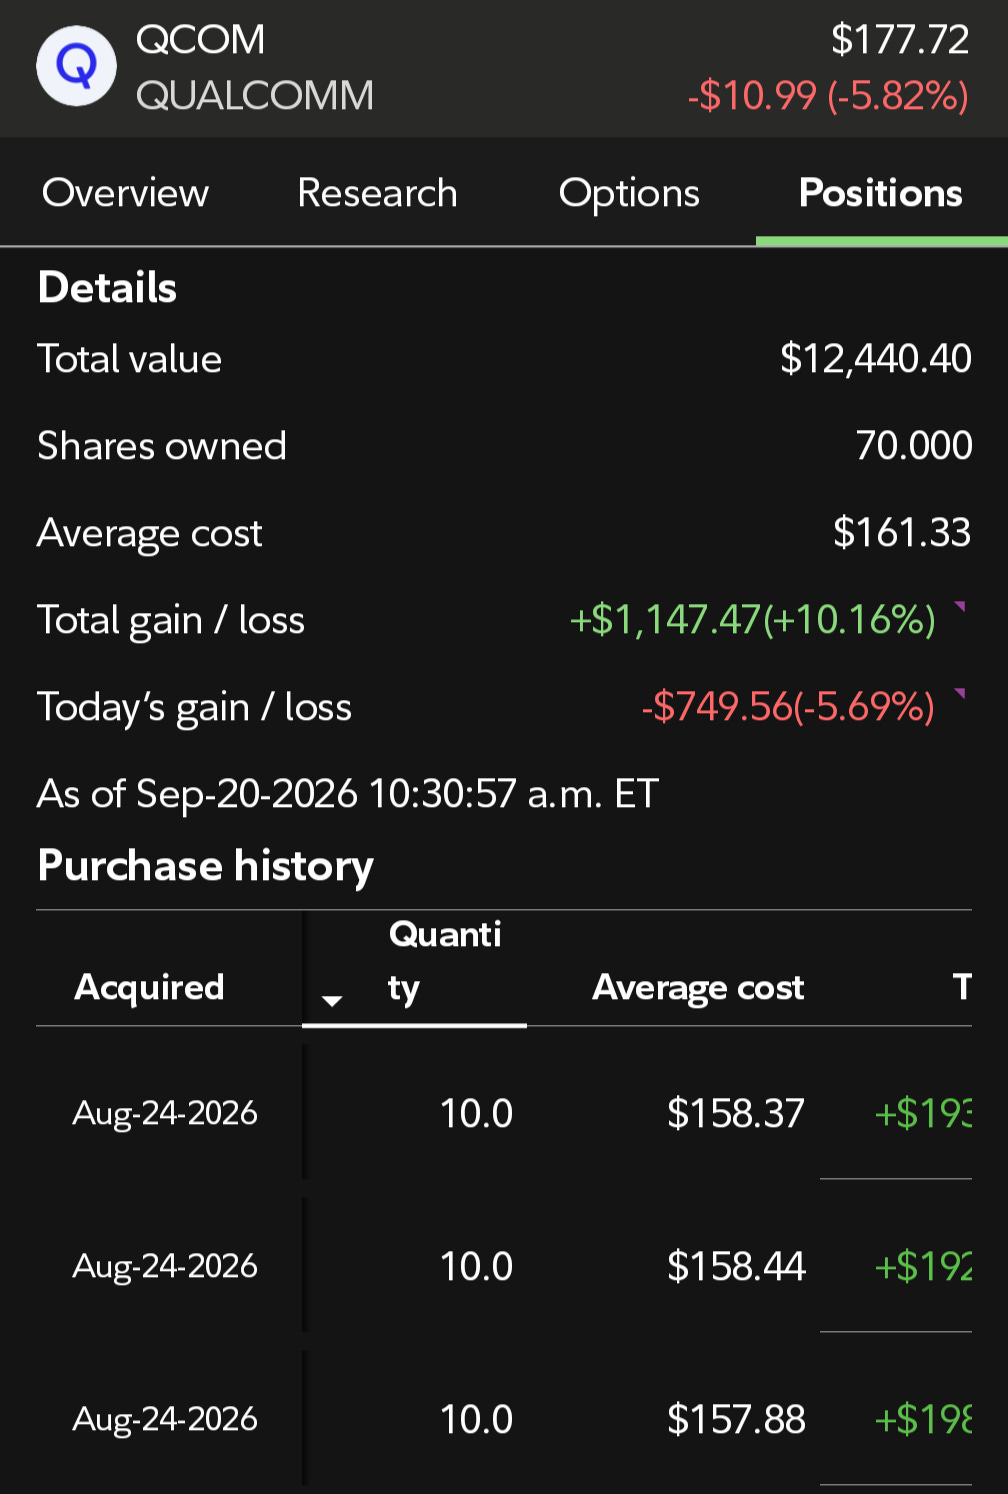
I own 70 shares of $QCOM. Average cost $161.33. Friday it dropped 5.82% and my broker app told me I'd lost $749.56 in one session, the kind of notification that makes you put the damn phone face down on the counter. Been that way a lot the last couple weeks.
Anyway, I reread the Amazon deal from September 8, slower. Amazon got warrants on 25 million Qualcomm shares. The strike is $161.26.
Seven cents. Amazon and I are long the same stock from the same price. One of us negotiated it (its lawyers did anyway), and one of us bought it in lots of ten coming off a $142 low because he liked the chart. Guess which?
I didn't know about the warrant when I bought - see the dates? Something I've found spending enough time in this market, and I've said it more than once but it's worth repeating here:
News follows price.
Insiders and institutions don't wait for the wire; their footprints show up in volume and structure first. You don't need to know why the bids are absorbing the float. You just need to respect that someone with larger pockets does.
I'm not going to pretend I saw Amazon coming, and I only did about a weekend of DD on the deal itself, so please do your own.
What paid gets this time
Normally the paid section is a write-up. This time it's the instrument. The TraderMatrix Apex levels for QCOM export as a TradingView Pine script, and paid subscribers get the actual file below the cut. Paste it into Pine Editor, hit Add to Chart, and the six magnets, the gamma flip, the entry band, the stop and the expected-move envelope draw on your own chart. Not a screenshot of mine.
It's a snapshot, not a live feed: open interest moves and the levels move with it. The file was generated this morning, so it's a map dated today.
The tape
Friday QCOM opened at $191.34, tagged $192.12, and closed $177.72. That's a 9.09% range on 54.4M shares, three times normal volume, the biggest bar of the whole six-week run. Open at the high, close near the low. A candle like that on that much volume is the market telling you where the sellers live.
Deal day did the same thing. September 8 it gapped from $168.74 to $180.40 on the Amazon news, printed $183.49, and closed at $174.09. Gave back more than half the gap before the bell. Twice the market has been handed the AI data-center story, and twice it sold into it.
Zoom out and this is attempt two at a data-center re-rate. QCOM ran from $120.88 in April to $257.56 by the end of May, then gave the entire thing back to $142 by August. Then it ran 35.2% in six weeks into Friday's high.
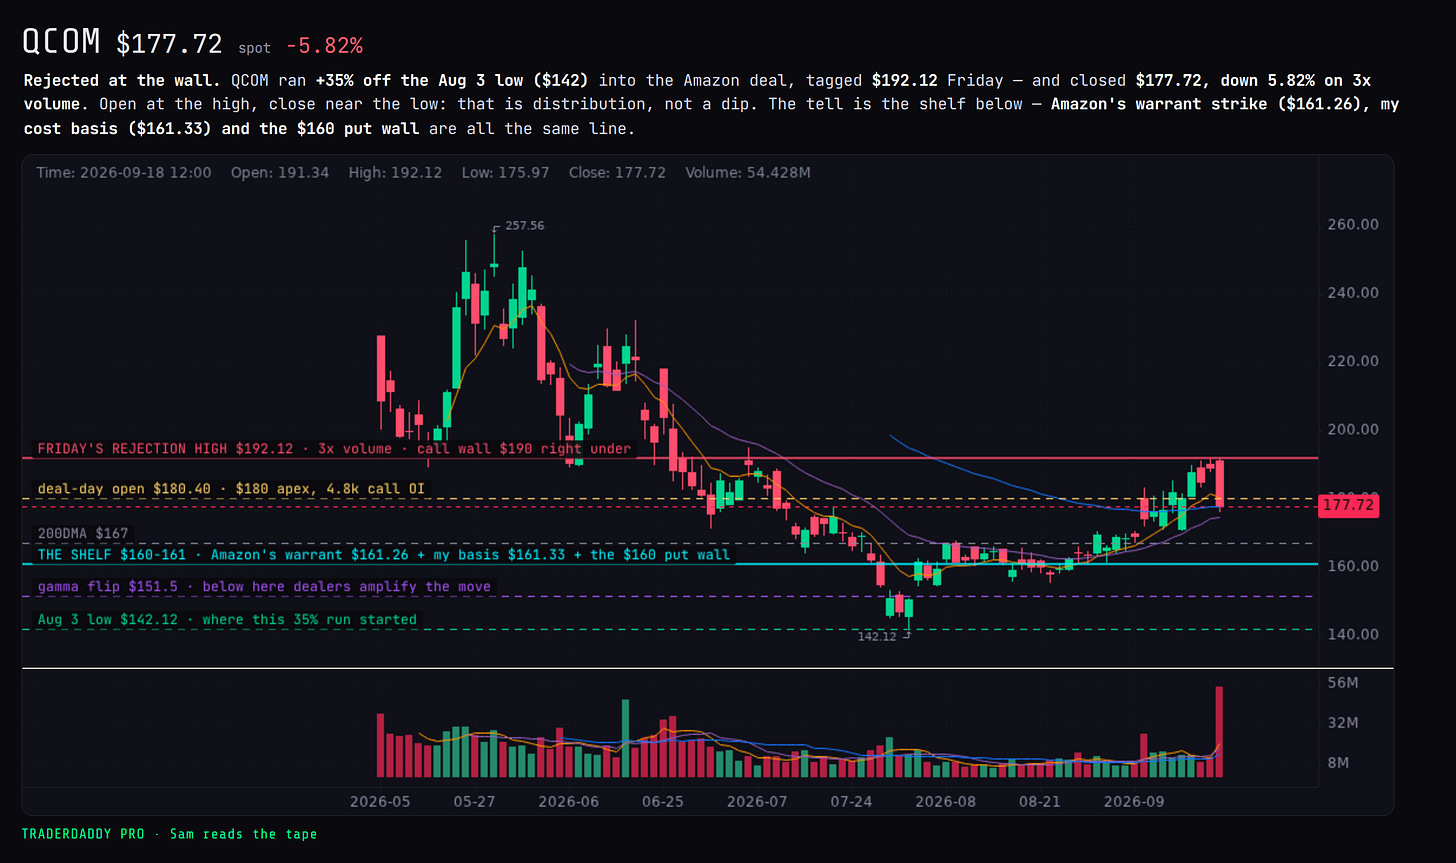
RSI rolled from 68.7 to 54.4. ADX is 22.9, barely a trend, just chop. It knifed through the 8 EMA and is holding above the 21. The 200-day is at $166.99, and the option chain has one real support strike, $160, right under my basis and Amazon's.
Amazon's strike, my cost, the 200-day and the put wall are stacked inside a $7 window. I don't get to claim I planned that, but I'll pretend anyway.
The deal, and the part to be careful with
Amazon: up to $60 billion of Qualcomm AI data-center silicon and systems, 2026 through 2036. Custom inference chips, AI200 this year and AI250 next. Revenue starts in December, with Qualcomm's own targets at about $5B in FY27 and $15B in FY29.
The $60 billion is not an order. It's a ceiling on the qualifying payments that count toward Amazon's warrants vesting. There's no backlog, and the deal supplements Trainium and Inferentia rather than replacing them.
Now the warrants. 25 million shares at $161.26, around $4 billion of stock, on 1.068 billion outstanding. That's 2.34% dilution. Qualcomm is paying a customer in equity to be a customer.
FY25 revenue was $44.3B at a 54.2% gross margin. Data-center silicon runs in the 30s to low 40s. Blend $15B of 35%-margin revenue onto that base:
(44.3 x 0.542 + 15 x 0.35) / (44.3 + 15) = 49.3%
Revenue up 34%, gross profit up 22%, five points of margin gone. That's what the escape from smartphones costs. Congratulations, Qualcomm: you traded a great-margin business for a slightly-worse one. Growth business, technically.
The bear case, stated fairly
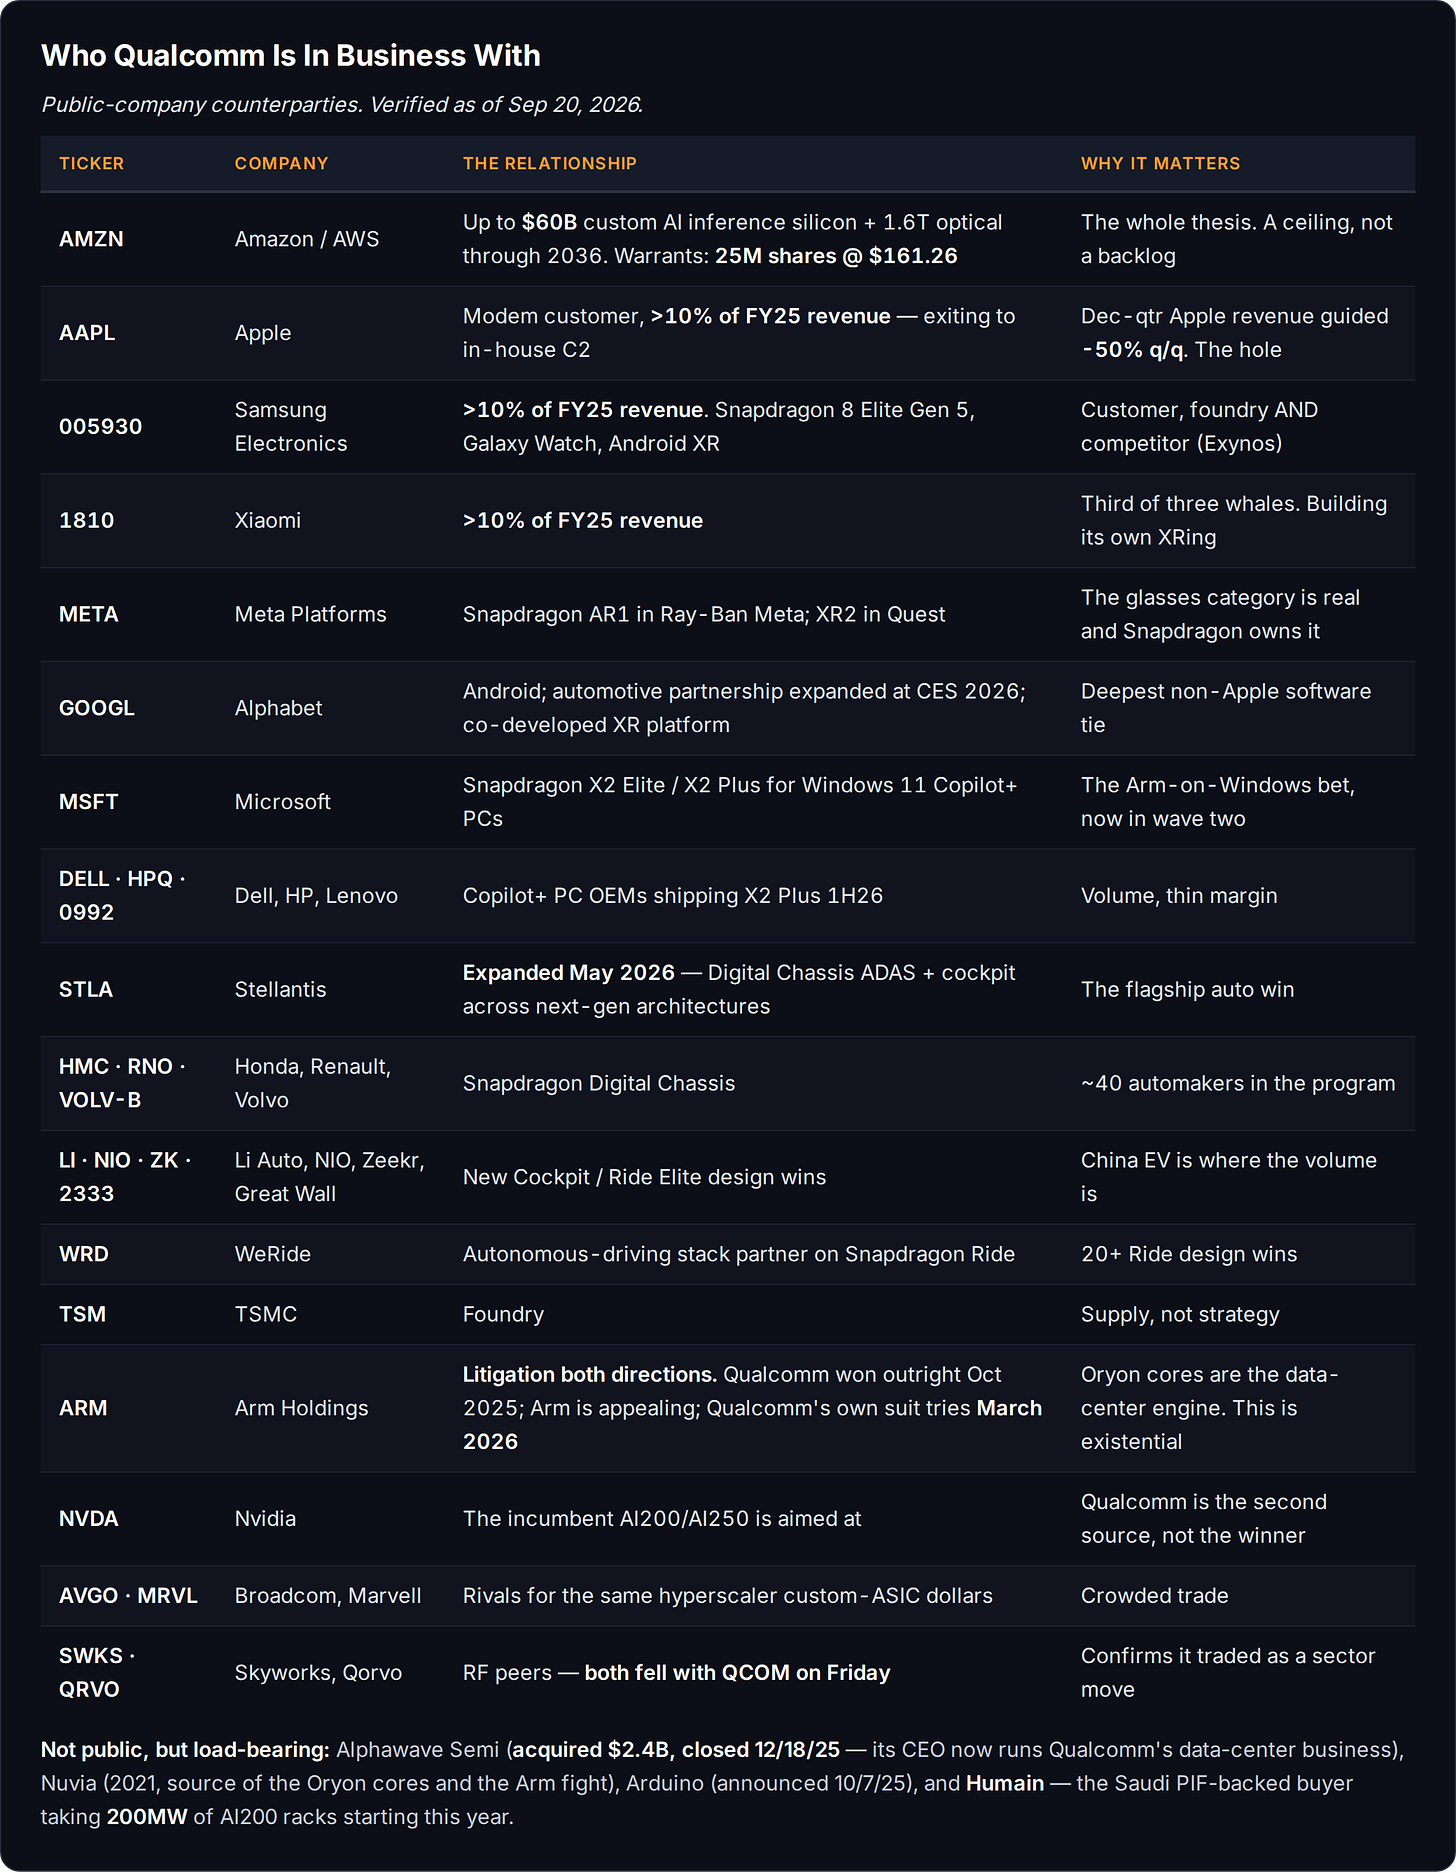
From the FY25 10-K: Apple, Samsung and Xiaomi each exceeded 10% of revenue. China including Hong Kong was 46%.
All three are building their own silicon. Apple's C2 modem is why Friday happened at all: Qualcomm said its share of upcoming iPhones lands well below the old ~20% assumption and guided Apple product revenue down about 50% sequentially into the December quarter. Samsung has Exynos. Xiaomi has XRing.
Nvidia is now getting a version of the same treatment Qualcomm is getting from Apple: fund the customer, watch the customer build its own chips. Qualcomm knows how that movie ends.
Two people who wrote about this before me
LongYield's piece is the one to read on the deal. He nailed the line that matters: "The $60 billion is not an order. It is a ceiling on the payments that can count toward a warrant vesting through 2036." And he says out loud that Qualcomm is trading licensing revenue that's nearly pure profit for data-center revenue in the thirties. The equity is the price of admission.
The Options Income wheel newsletter put QCOM in this week's free five: sell the $160 put, October 16 expiry, "about a 10% cushion." I checked it against the chain and it holds up. That put is $2.30 at the mid, 0.17 delta, a couple bucks under the options market's own one-sigma floor and right on a put wall with more than 4,000 contracts of open interest. Real strike, not a hope.
Calling a 0.17-delta put a "cushion" undersells it. That's roughly a one-in-six event, a moat until it isn't. Their framing also assumes you own none of it.